Health insurance covers medical bills, but disability insurance protects your paycheck. Learn how short- and long-term coverage works and why it matters.
Learn how Medicare enrollment can affect HSA contributions, why retroactive Part A coverage matters, and how to avoid potential excess contribution taxes.
Learn why your college student needs renter's insurance, what it costs, and how to choose the right coverage for dorms or off-campus housing.
2027 ACA Marketplace open enrollment dates continue to change. See the latest HealthCare.gov dates, key enrollment deadlines and what to know about state exchanges.
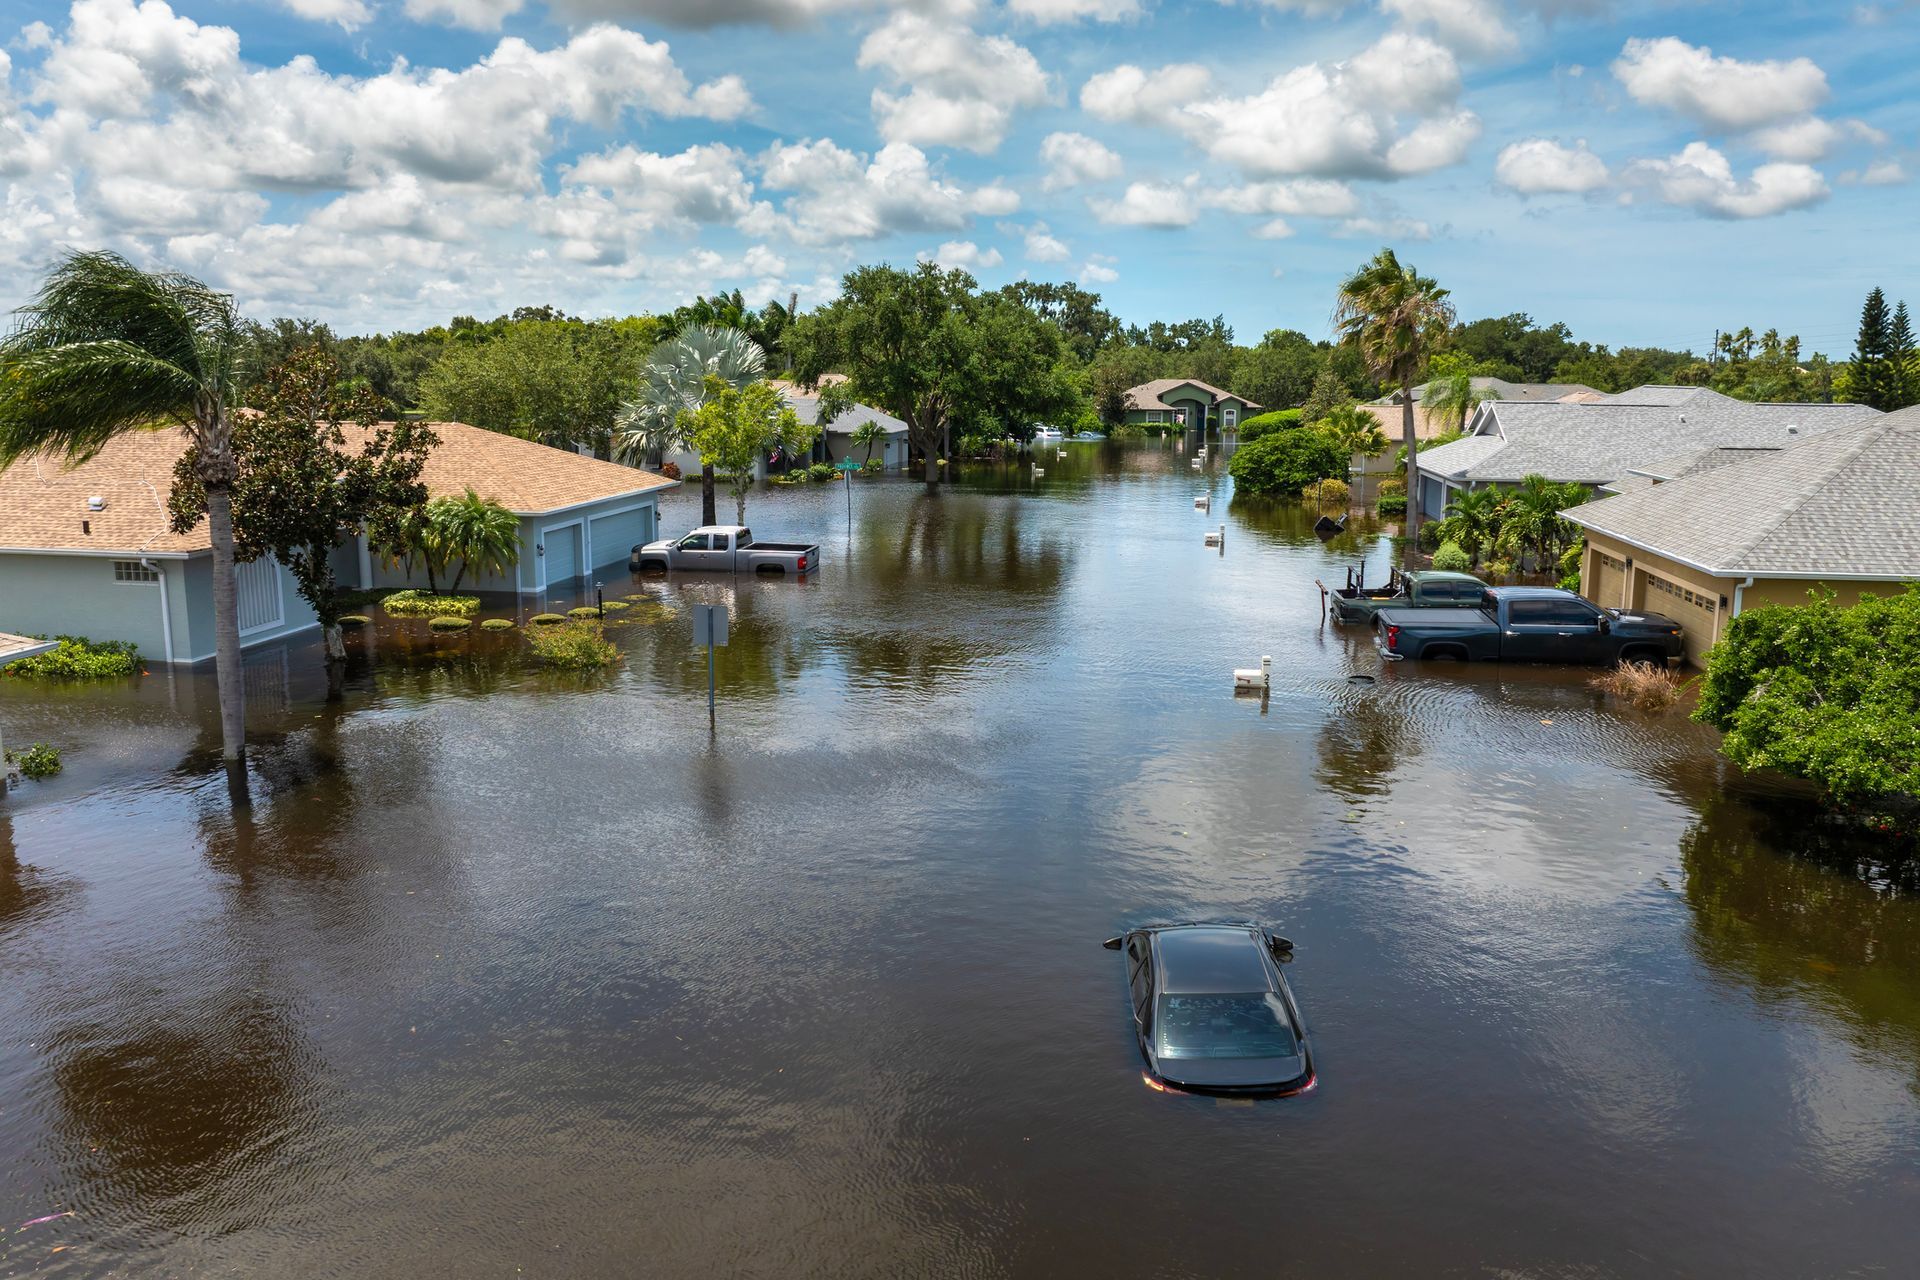
When we talk about disaster preparedness, most people think about emergency kits, canned goods, flashlights, and home evacuation plans. Some may even include homeowners or renters insurance in their checklist. But one crucial element is often overlooked: life insurance. While it may not seem like an immediate necessity when preparing for floods, wildfires, hurricanes, or earthquakes, life insurance plays a vital role in providing financial protection and peace of mind when the unexpected strikes. Why Financial Protection Matters in a Crisis Disasters, by nature, are unpredictable. They can upend lives in seconds, leaving families not only grieving, but also scrambling to manage expenses, cover debts, and rebuild. In the unfortunate event of a fatality during a disaster, the financial burden placed on surviving family members can be overwhelming. Life insurance helps to alleviate that burden. It offers a tax-free payout—known as a death benefit—that can help families cover funeral expenses, keep up with mortgage payments, manage day-to-day living costs, and plan for long-term needs like children’s education or retirement savings. It serves as a lifeline during the most difficult of times, helping loved ones maintain stability while navigating their grief. Support Beyond Loss: Life Insurance as a Financial Resource Life insurance doesn’t only serve its purpose in the event of death. Certain types of life insurance—particularly whole and universal life policies—accumulate cash value over time. That value can be accessed or borrowed against during emergencies. This is particularly important in disaster scenarios where families may be displaced, out of work, or waiting on slow-moving government aid or insurance claims. Having access to emergency funds through a life insurance policy can help pay for temporary housing, replace lost income, or cover other unexpected expenses that arise in the wake of a disaster. Filling the Gaps Left by Property Insurance Many people rely solely on homeowners or renters insurance to protect their assets, but these policies have limitations. They often exclude certain types of damages or may take weeks or months to payout, leaving families in a financial bind during recovery. Life insurance fills a different but equally important role by protecting the people—not just the property. It ensures that those who rely on your income or care will still be taken care of, no matter what happens. Business Owners: Safeguarding Operations and Legacy For small business owners, the stakes can be even higher. Disasters don’t just affect homes—they can also destroy businesses. In these situations, life insurance can play a critical role in protecting business continuity. It can fund buy-sell agreements, protect against the loss of a key employee or partner, and even serve as collateral for business loans. This type of coverage ensures that the company can survive long enough to recover or be transferred to new ownership, safeguarding not only the owner's legacy but also the livelihoods of employees and their families. Choosing the Right Coverage for Your Needs Selecting the right type of life insurance depends on your specific needs and goals. Term life insurance is typically more affordable and provides coverage for a set period, making it ideal for young families or those on a budget. Permanent policies like whole or universal life offer lifetime coverage and a savings component, which can be especially useful for long-term planning and emergency preparedness. Many insurers also offer policy riders—such as living benefits, critical illness coverage, or disability waivers—that can enhance your protection in high-risk situations, including natural disasters. Plan Ahead, Not After the Fact Ultimately, disaster preparedness isn’t just about having the right tools or supplies—it’s about having a plan that protects every aspect of your life, including the financial future of your loved ones. Life insurance is a critical part of that plan. It ensures that in the midst of chaos, your family or business won’t be left to pick up the financial pieces alone. The time to prepare is always before disaster strikes. Review your existing insurance policies, evaluate your family’s needs, and speak with a trusted advisor to determine the type and amount of life insurance that makes sense for your situation. With the right policy in place, you’ll be one step closer to protecting what matters most—no matter what tomorrow brings.

Learn what Medicare covers for skin cancer screenings, dermatologist visits, biopsies, and treatment, plus tips for prevention and early detection.

A clear guide to Health Insurance Marketplace metal tiers. Learn how Bronze, Silver, Gold, and Platinum plans split costs and how to pick the right one.

Discover how consistent daily routines improve sleep, mood, energy, and overall well-being—and how small habits can help your body thrive.

Learn how to prepare for health care costs in retirement, including Medicare, retiring before 65, long-term care, HSAs, and supplemental insurance options.

Help your employees choose the right health insurance plan. Learn the 6 most common open enrollment mistakes and how employers can help avoid them.