Breast Cancer Awareness Month: Turn Awareness Into Action

October 7, 2026

The Pink Ribbon Is a Reminder, Not the Finish Line


Every October, pink ribbons bring breast cancer into public view. And while awareness certainly matters, a more useful purpose to these cute little ribbons is personal action. To anyone with breasts, this means understanding your risk, paying attention to changes, talking with a healthcare professional about screening, and knowing how your insurance works before you need it.


Breast cancer can affect people with very different backgrounds and risk profiles. Women are affected most often, but men can develop breast cancer too. Some people have a strong family history or an inherited genetic change, while many people diagnosed have no obvious family history. No checklist can tell you with certainty who will or will not develop the disease.


Know What Is Normal for You


Breasts can naturally change with age, hormones, weight, pregnancy, and medications. Because of that variability of risk and of factors throughout life, it's crucial to become familiar with how your own breasts normally look and feel. That can be the key to making an unusual change easier to notice. Warning signs could include a new lump in the breast or underarm, thickening or swelling of tissue, skin dimpling or irritation, changes in size or shape, nipple changes, unusual discharge, or persistent pain.


If you do notice something, don't panic. Many breast changes are not cancer. Still, a new change is worth discussing with a healthcare professional, even if a recent mammogram was normal. Do not wait for a symptom to become severe before speaking up and asking a question.


Make Screening a Conversation


Mammogram can find some signs of breast cancer before symptoms appear. Recommendations about when to begin and how often to get these screenings depend on age, personal history, family history, breast density, genetic risk, and guidance from your healthcare team. Someone at higher risk may need more frequent mammograms or additional tests.


General rules, such as getting a mammogram once a year after the age of 40, are a good starting point, but you should also ask your doctor what is appropriate for you. Useful questions include when you should begin screening, how often you should return, whether you have risk factors that change the plan, and where to schedule the test.


Risk Information May Help You Plan


Some risk factors, including age and inherited genetic changes, cannot be controlled. Others may relate to health history or lifestyle. Gathering information can help guide conversations and provide context. Ask relatives what they know about cancers on both sides of the family, including the type of cancer and age at diagnosis. Share that history with your healthcare professional. If the pattern suggests increased risk, the next step might include a more detailed assessment or a discussion about genetic counseling. Be aware of lifestyle risk factors that you may need to change.


Understand Screening and Diagnostic Care


Insurance often treats a routine screening mammogram differently from a diagnostic mammogram ordered to evaluate a symptom or follow up on a finding. The services may look similar, but network rules and out-of-pocket costs can differ. Additional imaging, such as an ultrasound or MRI, may also have separate requirements regarding timing and referrals.


Before an appointment, consider asking your insurance company whether the facility is in network, whether an order or prior authorization is needed, and what costs may apply if the visit becomes diagnostic. You can also reach out to us for help understanding the terms of your policy. Coverage varies by plan, age, risk level, and the reason for the service, so confirm the details rather than assuming every test will be handled the same way.


Review the Rest of Your Financial Safety Net


A cancer diagnosis can affect more than medical bills. Time away from work, travel for treatment, household help, and other everyday expenses can put pressure on a family. Health insurance is central to treatment, but it may not address every financial consequence.


This month can be a useful time to review your health plan's deductible, out-of-pocket limit, prescription coverage, provider network, and care-management resources. Depending on your situation, you may also want to understand disability, critical illness, cancer coverage, hospital indemnity, or life insurance already in place. These products have limitations and exclusions, and they should not be treated as substitutes for major medical coverage.


Support Can Be Practical as Well as Emotional


If someone you care about is dealing with breast cancer, specific offers are often easier to accept than a general request to call if anything is needed. A ride, a meal, a fun activity, help with errands, childcare, or simply listening can reduce the weight of a difficult week. Respect the person's privacy and follow their lead about what they want to share.


Choose One Step This October


Awareness is truly meaningful when it leads to action. This month, take at least one action to help stop breast cancer. Schedule an overdue appointment, write down your family history, ask your doctor about a screening, or review your coverage. If you have questions about how your insurance may handle mammograms, diagnostic testing, prescriptions, or specialist care, contact our office. We can help you understand the plan language and prepare more informed questions for your healthcare team.

Person seated at a table using a smartphone in a cozy living room, with a coffee cup nearby.
October 14, 2026
AI can help scammers create convincing images, voices, and documents. Learn the warning signs and simple steps that can help protect your insurance information.
Woman reclining on an orange couch resting her arm on her forehead
September 30, 2026
Could you afford to miss months of work due to illness or injury? Learn how disability insurance replaces lost income, why coverage rates are low, and what steps to take to protect your financial future.
Senior couple relaxing together on a park bench outdoors
September 27, 2026
Learn how annuities can provide guaranteed retirement income, help manage longevity risk, and add stability to a retirement strategy during uncertain markets.
Person resting on a couch under a teal blanket
September 24, 2026
GLP-1 medications help you eat less — but eating less can mean fewer nutrients. Here's what the latest research shows and how to eat well.
Woman with a headscarf resting on a couch holding a mug
September 21, 2026
Health insurance covers medical bills, but disability insurance protects your paycheck. Learn how short- and long-term coverage works and why it matters.
Couple reviewing a document with an insurance advisor at a table
September 17, 2026
Online calculators are only a starting point. Here is a simple four-part way to think through how much life insurance fits your family and your budget.
Senior couple looking at a phone and a red card together
September 13, 2026
Learn how Medicare enrollment can affect HSA contributions, why retroactive Part A coverage matters, and how to avoid potential excess contribution taxes.
Young people relaxing on the floor of a dorm room with luggage
September 9, 2026
Learn why your college student needs renter's insurance, what it costs, and how to choose the right coverage for dorms or off-campus housing.
Person in a tan shirt typing on a laptop keyboard
September 5, 2026
2027 ACA Marketplace open enrollment dates continue to change. See the latest HealthCare.gov dates, key enrollment deadlines and what to know about state exchanges.
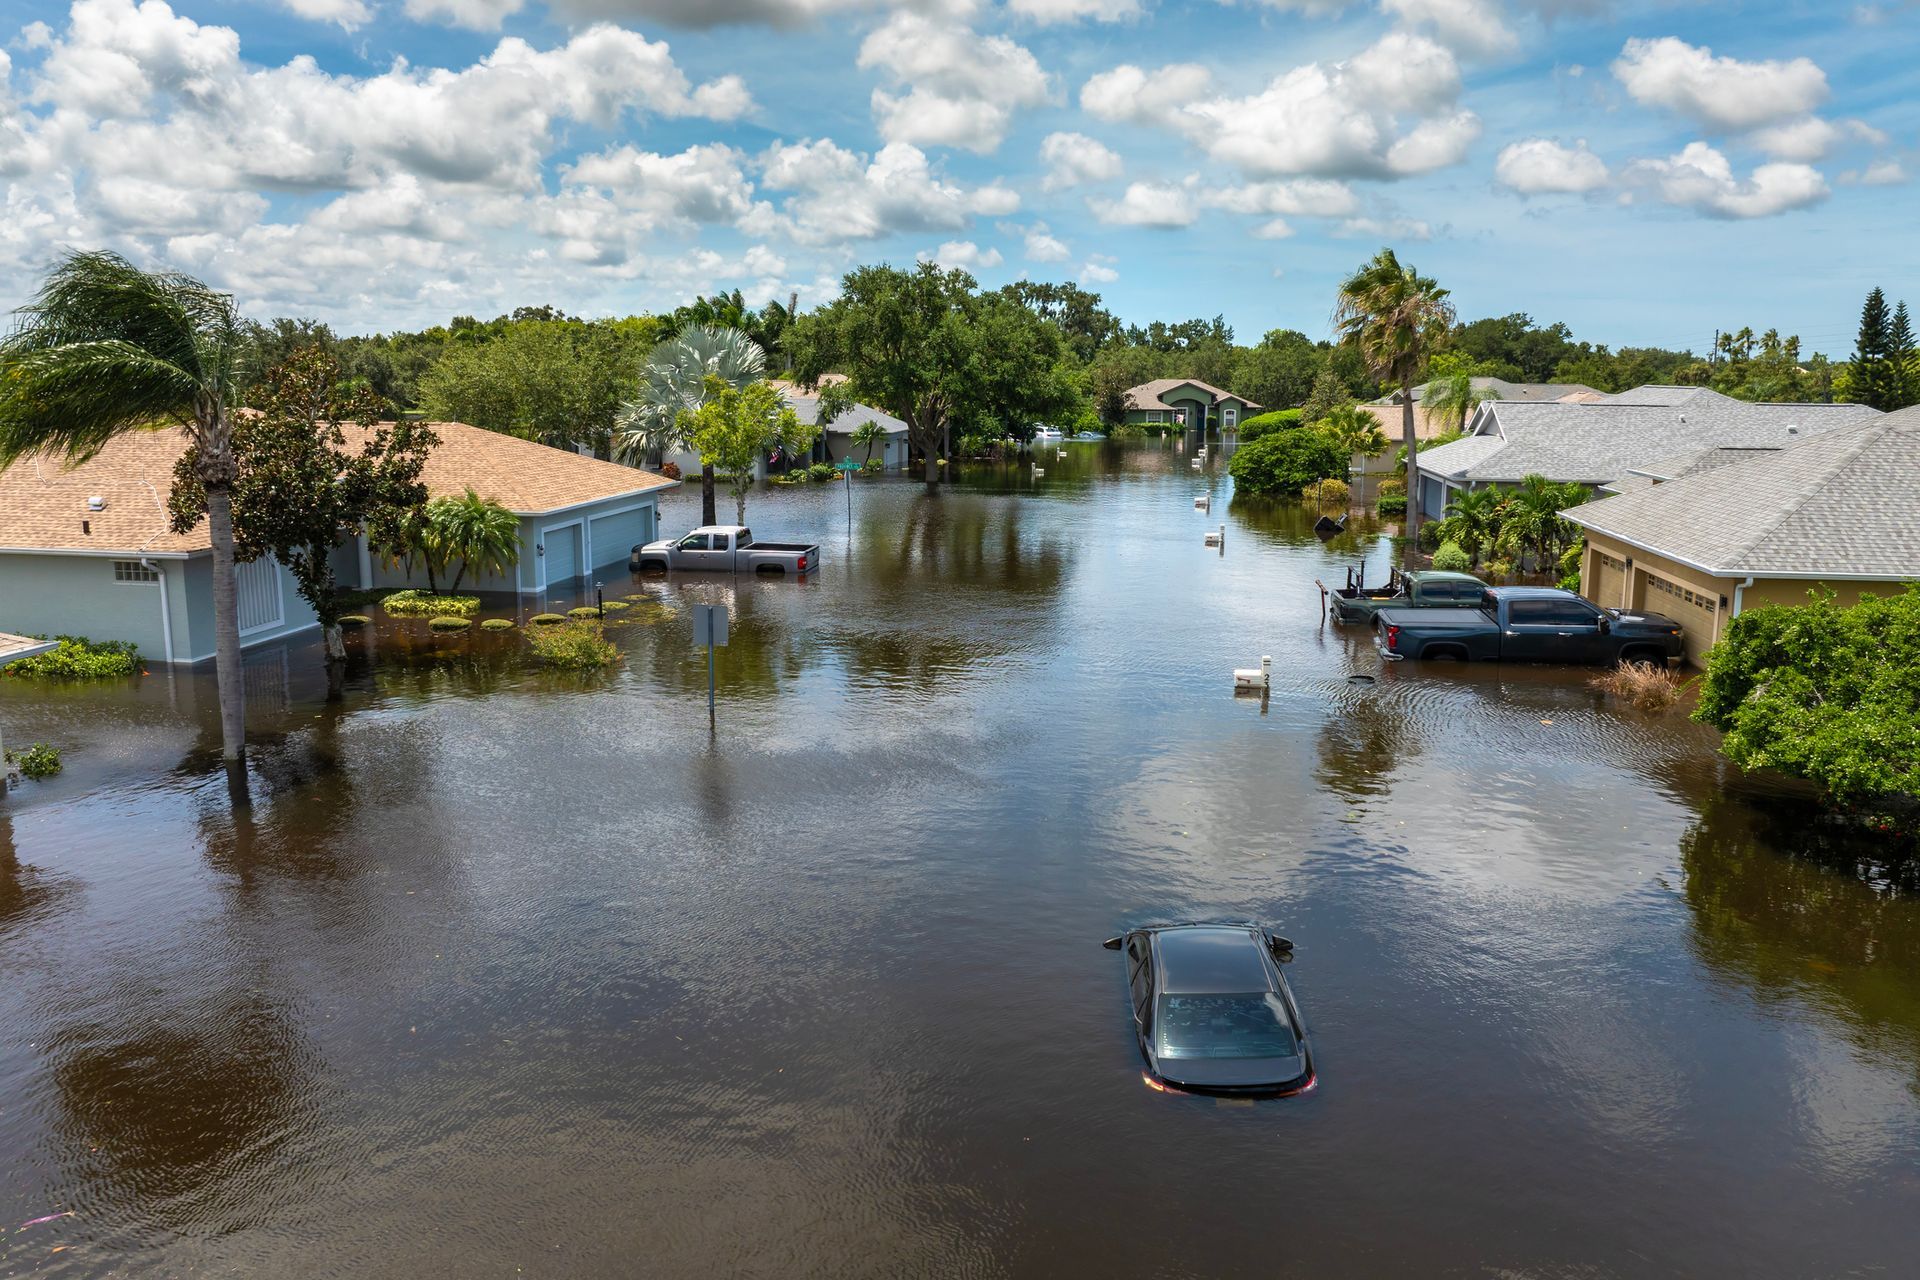
Flooded residential street with submerged cars and homes under a cloudy sky
By Newhouse Financial Group • September 1, 2026
When we talk about disaster preparedness, most people think about emergency kits, canned goods, flashlights, and home evacuation plans. Some may even include homeowners or renters insurance in their checklist. But one crucial element is often overlooked: life insurance. While it may not seem like an immediate necessity when preparing for floods, wildfires, hurricanes, or earthquakes, life insurance plays a vital role in providing financial protection and peace of mind when the unexpected strikes. Why Financial Protection Matters in a Crisis Disasters, by nature, are unpredictable. They can upend lives in seconds, leaving families not only grieving, but also scrambling to manage expenses, cover debts, and rebuild. In the unfortunate event of a fatality during a disaster, the financial burden placed on surviving family members can be overwhelming.  Life insurance helps to alleviate that burden. It offers a tax-free payout—known as a death benefit—that can help families cover funeral expenses, keep up with mortgage payments, manage day-to-day living costs, and plan for long-term needs like children’s education or retirement savings. It serves as a lifeline during the most difficult of times, helping loved ones maintain stability while navigating their grief. Support Beyond Loss: Life Insurance as a Financial Resource Life insurance doesn’t only serve its purpose in the event of death. Certain types of life insurance—particularly whole and universal life policies—accumulate cash value over time. That value can be accessed or borrowed against during emergencies. This is particularly important in disaster scenarios where families may be displaced, out of work, or waiting on slow-moving government aid or insurance claims. Having access to emergency funds through a life insurance policy can help pay for temporary housing, replace lost income, or cover other unexpected expenses that arise in the wake of a disaster. Filling the Gaps Left by Property Insurance Many people rely solely on homeowners or renters insurance to protect their assets, but these policies have limitations. They often exclude certain types of damages or may take weeks or months to payout, leaving families in a financial bind during recovery. Life insurance fills a different but equally important role by protecting the people—not just the property. It ensures that those who rely on your income or care will still be taken care of, no matter what happens. Business Owners: Safeguarding Operations and Legacy For small business owners, the stakes can be even higher. Disasters don’t just affect homes—they can also destroy businesses. In these situations, life insurance can play a critical role in protecting business continuity. It can fund buy-sell agreements, protect against the loss of a key employee or partner, and even serve as collateral for business loans. This type of coverage ensures that the company can survive long enough to recover or be transferred to new ownership, safeguarding not only the owner's legacy but also the livelihoods of employees and their families. Choosing the Right Coverage for Your Needs Selecting the right type of life insurance depends on your specific needs and goals. Term life insurance is typically more affordable and provides coverage for a set period, making it ideal for young families or those on a budget. Permanent policies like whole or universal life offer lifetime coverage and a savings component, which can be especially useful for long-term planning and emergency preparedness. Many insurers also offer policy riders—such as living benefits, critical illness coverage, or disability waivers—that can enhance your protection in high-risk situations, including natural disasters. Plan Ahead, Not After the Fact Ultimately, disaster preparedness isn’t just about having the right tools or supplies—it’s about having a plan that protects every aspect of your life, including the financial future of your loved ones. Life insurance is a critical part of that plan. It ensures that in the midst of chaos, your family or business won’t be left to pick up the financial pieces alone. The time to prepare is always before disaster strikes. Review your existing insurance policies, evaluate your family’s needs, and speak with a trusted advisor to determine the type and amount of life insurance that makes sense for your situation. With the right policy in place, you’ll be one step closer to protecting what matters most—no matter what tomorrow brings.
Show More