Are You Getting Enough Nutrients on GLP-1 Medication?

September 24, 2026

What the Latest Research Says About GLP-1s, Nutrition Gaps, and Getting Enough of What Matters


If you're using a popular GLP-1 medication like Ozempic, Zepbound or Wegovy for weight loss, it's important to be mindful of your nutrition, because you're probably eating significantly less than you used to. A recent review found that total caloric intake dropped by 16% to 39% in patients taking a GLP-1.


These medications help you feel full faster, so you eat less, which can lead to significant weight loss. But that same reduced appetite has a downside: it can mean you aren't taking in enough of the essential nutrients your body needs to stay healthy.


Some people taking GLP-1 medications say they don't feel hungry, skip eating for most of the day, or have just one large meal in the evening. And plenty of people on these drugs never change the kind of food they eat — they simply eat smaller amounts of the same less-healthy choices. The result is fewer calories and less variety, which is a recipe for missing key nutrients.


What the Latest Research Shows


This isn't just anecdotal. A narrative review published in Clinical Obesity in early 2026 pooled six studies covering more than 480,000 adults with diabetes, obesity, or both who were taking GLP-1 drugs. The researchers concluded that nutritional deficiencies should be considered "a common consequence" of GLP-1 therapy, and that doctors should monitor patients accordingly.


A few highlights from that research:


• Vitamin D deficiency was the most common problem, affecting about 13.6% of participants after 12 months of treatment in the largest study.

• Iron deficiency (around 3.2%) and B vitamin deficiency (around 2.6%) also showed up, along with anemia tied to poor nutrition (about 4%).

• Deficiencies tended to worsen the longer people stayed on treatment — more were diagnosed at 12 months than at 6 months.

• In a smaller study that tracked detailed food diaries, the gaps were striking: many participants fell short on calcium, nearly two-thirds didn't get enough iron, and almost none met the recommendation for vitamin D.


It's worth noting these findings come largely from observational data, so they show a strong association rather than ironclad proof of cause and effect. Still, the pattern is consistent enough that nutrition deserves real attention while you're on these medications.


What Happens When You Don't Get Enough


Falling short on nutrients can show up in ways that are easy to write off as "just part of losing weight," but shouldn't be ignored:


• Fatigue and dizziness — often linked to low iron, low calorie intake, or not drinking enough fluids.

• Muscle loss — too little protein can lead to a progressive loss of muscle mass and strength. This is a real concern on GLP-1s, since rapid weight loss can include muscle, not just fat.

• Digestive issues like constipation — frequently a sign of too little fiber and water.

• Hair and skin problems — a common downstream effect of overall undernutrition.


What to Eat and Drink for Balanced Nutrition


Even when your appetite is low, the right food choices go a long way toward preventing these problems. The key is quality over quantity: with fewer bites to work with, each one should count. Aim to build meals around protein, healthy fats, whole grains, and plenty of fruits and vegetables.


Protein


• Lean meats (chicken, turkey)

• Fish and seafood

• Eggs

• Plant-based proteins like beans, lentils, tofu and soy products

• Low-fat dairy (yogurt, milk, cheese)


Fiber


• Whole grains (oats, quinoa, brown rice)

• Vegetables (broccoli, carrots, spinach, kale)

• Fruits (apples, oranges, berries)

• Nuts, seeds and legumes


Healthy fats


• Avocados

• Nuts and seeds

• Olive oil and other plant-based oils

• Fatty fish (salmon, tuna, mackerel)


Hydration


• Water (aim for 8–10 glasses a day)

• Low-calorie drinks (herbal tea, unsweetened beverages)

• Nutrient-dense drinks like low-fat milk or soy milk

• Limit sugary sodas, excess caffeine, and alcohol


Additional Tips for Staying Healthy


• Listen to your body. Fatigue, muscle loss, or constipation can all be signs that you're not getting enough nutrients or fluids.

• Don't skip meals entirely. Going without food all day can lead to malnutrition over time, even if you're not hungry.

• Consider meal replacement shakes or bars if your appetite is very low — they can help you hit your protein and vitamin targets when whole meals feel like too much.

• Add a daily multivitamin and supplements if your doctor recommends it. Given how often vitamin D, iron, and B vitamins come up in the research, this is a reasonable conversation to have.

• Keep moving. Light to moderate exercise — especially walking and resistance training — helps preserve muscle and enhances the benefits of the medication.

• Ask about bloodwork. If you've been on a GLP-1 for several months, periodic lab checks can catch a developing deficiency before it causes symptoms.


GLP-1 medications can be a powerful tool for weight loss and metabolic health. Getting the nutrition piece right is what helps you feel strong and energized along the way — not just lighter on the scale.

Senior couple relaxing together on a park bench outdoors
September 27, 2026
Learn how annuities can provide guaranteed retirement income, help manage longevity risk, and add stability to a retirement strategy during uncertain markets.
Woman with a headscarf resting on a couch holding a mug
September 21, 2026
Health insurance covers medical bills, but disability insurance protects your paycheck. Learn how short- and long-term coverage works and why it matters.
Couple reviewing a document with an insurance advisor at a table
September 17, 2026
Online calculators are only a starting point. Here is a simple four-part way to think through how much life insurance fits your family and your budget.
Senior couple looking at a phone and a red card together
September 13, 2026
Learn how Medicare enrollment can affect HSA contributions, why retroactive Part A coverage matters, and how to avoid potential excess contribution taxes.
Young people relaxing on the floor of a dorm room with luggage
September 9, 2026
Learn why your college student needs renter's insurance, what it costs, and how to choose the right coverage for dorms or off-campus housing.
Person in a tan shirt typing on a laptop keyboard
September 5, 2026
2027 ACA Marketplace open enrollment dates continue to change. See the latest HealthCare.gov dates, key enrollment deadlines and what to know about state exchanges.
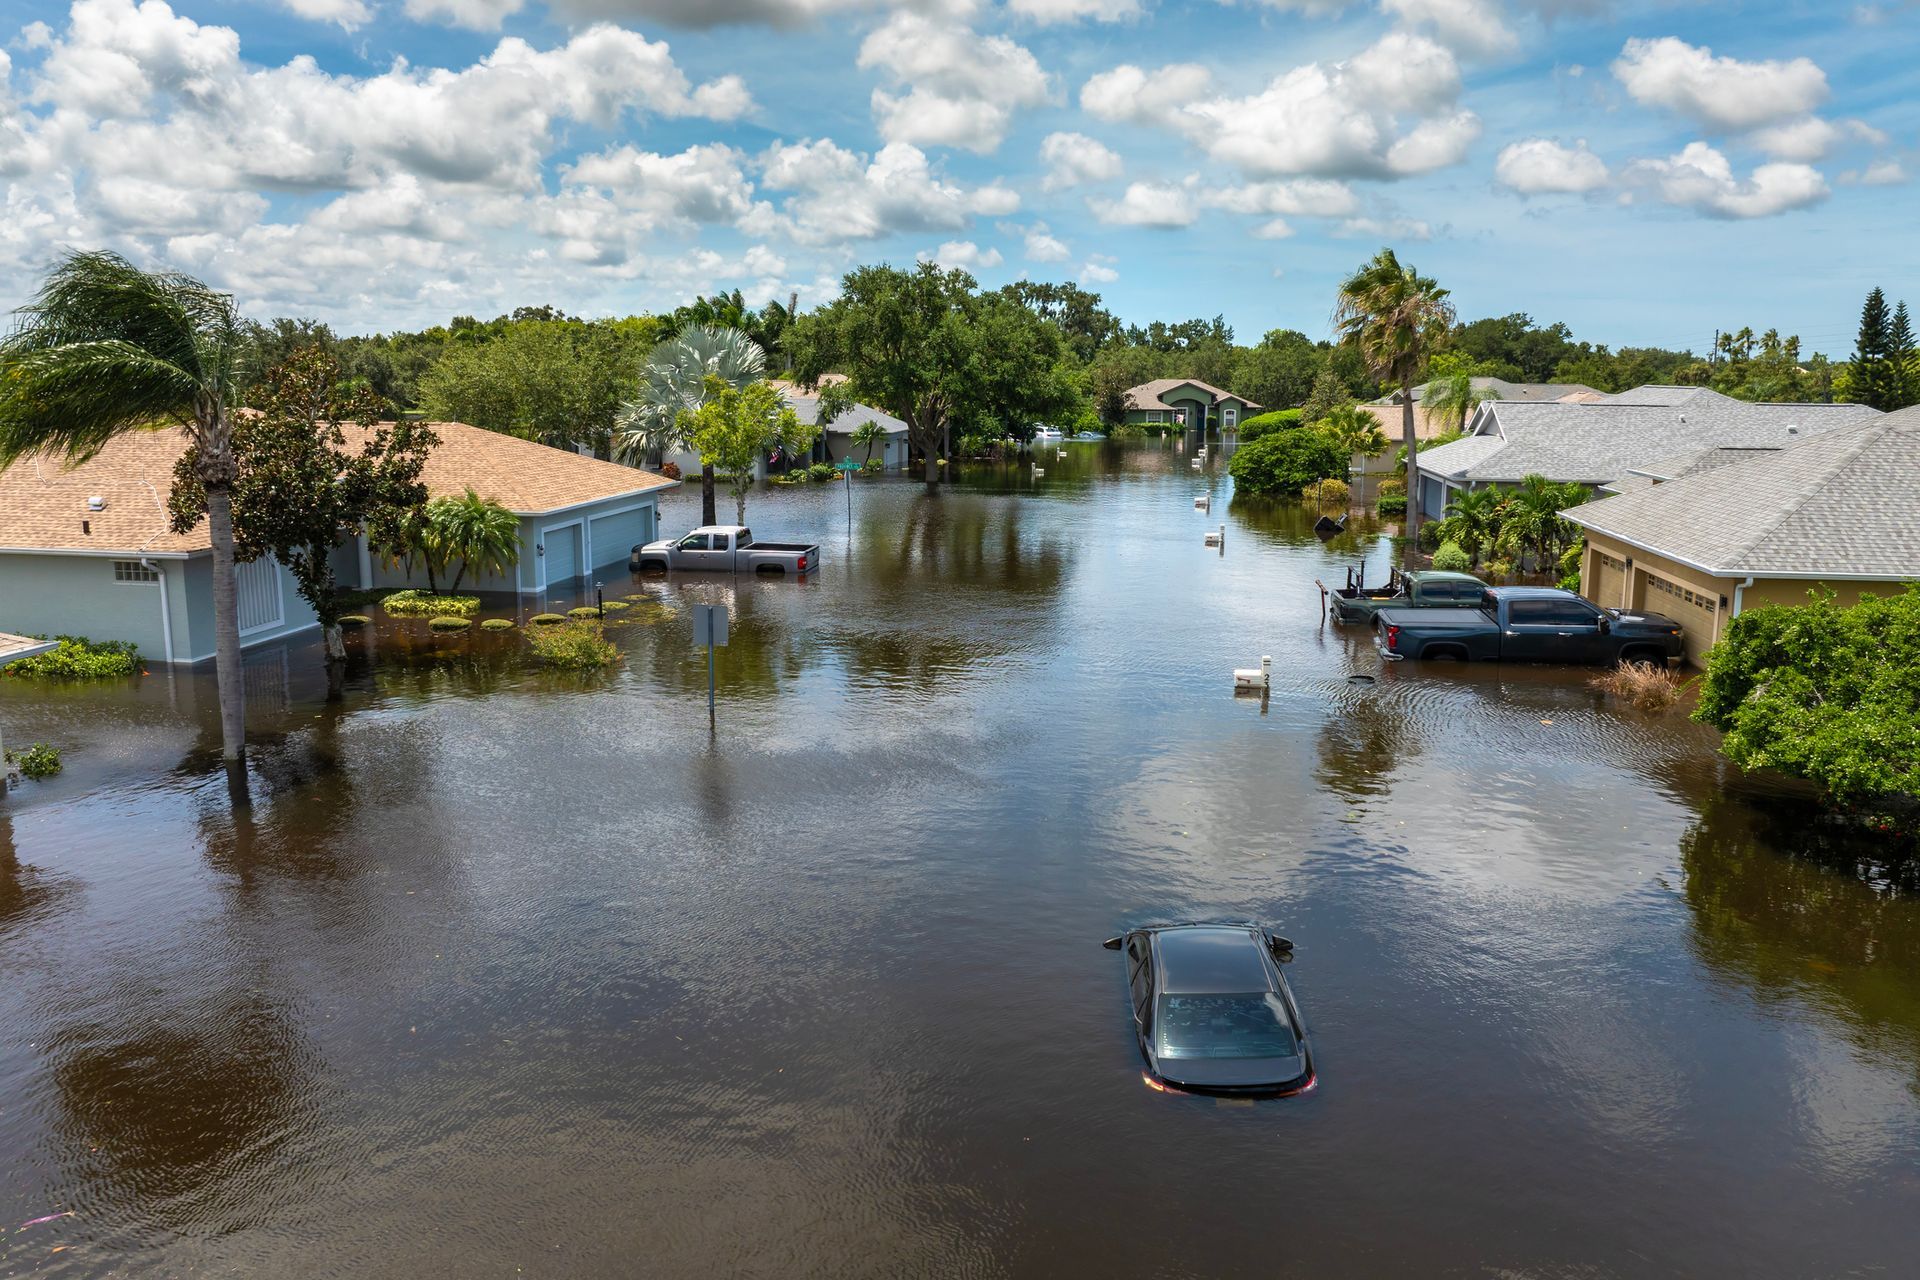
Flooded residential street with submerged cars and homes under a cloudy sky
By Newhouse Financial Group • September 1, 2026
When we talk about disaster preparedness, most people think about emergency kits, canned goods, flashlights, and home evacuation plans. Some may even include homeowners or renters insurance in their checklist. But one crucial element is often overlooked: life insurance. While it may not seem like an immediate necessity when preparing for floods, wildfires, hurricanes, or earthquakes, life insurance plays a vital role in providing financial protection and peace of mind when the unexpected strikes. Why Financial Protection Matters in a Crisis Disasters, by nature, are unpredictable. They can upend lives in seconds, leaving families not only grieving, but also scrambling to manage expenses, cover debts, and rebuild. In the unfortunate event of a fatality during a disaster, the financial burden placed on surviving family members can be overwhelming.  Life insurance helps to alleviate that burden. It offers a tax-free payout—known as a death benefit—that can help families cover funeral expenses, keep up with mortgage payments, manage day-to-day living costs, and plan for long-term needs like children’s education or retirement savings. It serves as a lifeline during the most difficult of times, helping loved ones maintain stability while navigating their grief. Support Beyond Loss: Life Insurance as a Financial Resource Life insurance doesn’t only serve its purpose in the event of death. Certain types of life insurance—particularly whole and universal life policies—accumulate cash value over time. That value can be accessed or borrowed against during emergencies. This is particularly important in disaster scenarios where families may be displaced, out of work, or waiting on slow-moving government aid or insurance claims. Having access to emergency funds through a life insurance policy can help pay for temporary housing, replace lost income, or cover other unexpected expenses that arise in the wake of a disaster. Filling the Gaps Left by Property Insurance Many people rely solely on homeowners or renters insurance to protect their assets, but these policies have limitations. They often exclude certain types of damages or may take weeks or months to payout, leaving families in a financial bind during recovery. Life insurance fills a different but equally important role by protecting the people—not just the property. It ensures that those who rely on your income or care will still be taken care of, no matter what happens. Business Owners: Safeguarding Operations and Legacy For small business owners, the stakes can be even higher. Disasters don’t just affect homes—they can also destroy businesses. In these situations, life insurance can play a critical role in protecting business continuity. It can fund buy-sell agreements, protect against the loss of a key employee or partner, and even serve as collateral for business loans. This type of coverage ensures that the company can survive long enough to recover or be transferred to new ownership, safeguarding not only the owner's legacy but also the livelihoods of employees and their families. Choosing the Right Coverage for Your Needs Selecting the right type of life insurance depends on your specific needs and goals. Term life insurance is typically more affordable and provides coverage for a set period, making it ideal for young families or those on a budget. Permanent policies like whole or universal life offer lifetime coverage and a savings component, which can be especially useful for long-term planning and emergency preparedness. Many insurers also offer policy riders—such as living benefits, critical illness coverage, or disability waivers—that can enhance your protection in high-risk situations, including natural disasters. Plan Ahead, Not After the Fact Ultimately, disaster preparedness isn’t just about having the right tools or supplies—it’s about having a plan that protects every aspect of your life, including the financial future of your loved ones. Life insurance is a critical part of that plan. It ensures that in the midst of chaos, your family or business won’t be left to pick up the financial pieces alone. The time to prepare is always before disaster strikes. Review your existing insurance policies, evaluate your family’s needs, and speak with a trusted advisor to determine the type and amount of life insurance that makes sense for your situation. With the right policy in place, you’ll be one step closer to protecting what matters most—no matter what tomorrow brings.
Smiling person in a white cowboy hat outdoors, with a hand raised near their face.
By No author • September 1, 2026
Learn what Medicare covers for skin cancer screenings, dermatologist visits, biopsies, and treatment, plus tips for prevention and early detection.
Four vertical panels of gold, silver, bronze, and gray bars in coin piles
By No author • September 1, 2026
A clear guide to Health Insurance Marketplace metal tiers. Learn how Bronze, Silver, Gold, and Platinum plans split costs and how to pick the right one.
Runner’s legs in motion on a wet city sidewalk beside a glass building
By No author • September 1, 2026
Discover how consistent daily routines improve sleep, mood, energy, and overall well-being—and how small habits can help your body thrive.
Show More